Affirm: Buy now, pay over time

- 228.55K Reviews
- 4.8
- Downloads
- 10,000,000+
 Analysis by Appgk
I think of Affirm as a checkout and repayment tool for people who want to spread the cost of a purchase without losing sight of what they’ll owe. It sits in the shopping category, but it is not a store where you browse a general catalogue and fill a cart. Its job is to help you review payment options for eligible purchases and keep track of the plan you choose. That difference matters: it can make a planned expense easier to manage, but it does not make an impulse purchase more affordable.
Where the app fits today
Affirm, made by Affirm, Inc, is free to download and is rated for Everyone. It has an average rating of 4.8 from around 532,000 ratings, with over 10 million installs, so it has become a familiar name for shoppers looking for another way to pay. The current version is 3.402.1, and the app is listed for devices running Android 7.0 or later. Those details describe the current product snapshot; they are not a promise that every checkout, retailer, or payment plan will work the same way for every person.
The useful question is not simply whether paying over time sounds convenient. It is whether a particular purchase fits your budget and whether the terms shown at checkout are better for you than paying upfront or using another payment method. I’d treat the app as a way to inspect and manage a payment choice, not as permission to spend beyond what I can reasonably repay.
What its version history means for shoppers
The app was released on June 20, 2016, and the current version number shows that it has continued to develop since then. A version number alone does not tell me which functions changed or when a specific feature arrived, so I wouldn’t read it as evidence of a particular improvement. What matters for an existing user is the experience in the installed app now: check the payment details displayed for the purchase in front of you, and make sure the plan still suits your circumstances before confirming it.
For someone who already uses Affirm, that practical habit is more valuable than assuming an old checkout will match a new one. Retailer choices, the purchase, and the terms presented can affect what is offered. If you have not opened the app in a while, take a moment to review your account and upcoming payments rather than relying on memory or an old plan you saw elsewhere.
What is Affirm All About?
If you haven't heard of it yet, Affirm is a nifty little app that partners with a ton of retailers to provide a transparent and straightforward way to finance your purchases. You know how sometimes you see that perfect gadget or pair of shoes, but the price tag makes you hesitate? Affirm lets you split that cost into manageable monthly payments. Pretty cool, right?
Getting Started with Affirm
Setting up Affirm is a breeze. You download the app, create an account, and provide some basic information to get started. What I love about it is how quick and seamless the process is. No more filling out endless forms or waiting for approval. It’s all about giving you that instant gratification.
News Picks to Read Next
View All News


Once you're set up, you can start shopping with their partner stores. When you’re ready to checkout, choose Affirm as your payment option. You'll receive a breakdown of your payment plan, including interest rates and monthly installments, before you commit. This way, you know exactly what you’re getting into.
Reading the offer before tapping confirm
For me, the most useful point in the process is the pause before accepting a plan. I would compare the scheduled payments with bills that already leave my account, then consider the total amount due rather than judging the offer by its monthly figure alone. A smaller installment can feel easy in isolation but become awkward when it overlaps with rent, utilities, or another purchase.
Best Parts of Affirm: Buy now, pay over time
Things to Keep in Mind About Affirm: Buy now, pay over time
It is also worth checking whether the plan presented is the one you expected. Read the displayed schedule and cost carefully, and save or note the information in a way you can find later. If the terms do not work for your budget, backing out and paying another way is a sensible decision, not a failure to use the app.
The User Experience
Using Affirm feels like having a financial buddy who’s got your back. The app’s interface is sleek and user-friendly, making it easy to navigate through your purchases, payment schedules, and account details. Plus, it’s packed with features like alerts and reminders, so you’ll never miss a payment.
One aspect that stood out to me is the transparency. Affirm doesn’t hide any fees or penalties. What you see is what you pay, and that level of honesty is refreshing. It’s like having a financial advisor who actually tells you everything upfront.
Everyday use: keeping one planned purchase manageable
Imagine your household appliance stops working shortly before payday. You find a replacement at a participating retailer, compare the payment option with the upfront price, and check whether the schedule fits your next few months. If it does, the app can help you handle a necessary expense without paying the full amount on that day. If you would need to miss another bill to make the installments, the same comparison tells you to wait, choose a cheaper model, or use a different payment method.
That is the kind of situation where I see a practical role for Affirm: a deliberate purchase with a clear purpose and room in the budget. I would be more cautious about using it for several small wants in quick succession. Each plan may look manageable alone, while the combined commitments are harder to keep in view. Before starting another one, I’d look at all existing payment dates together and ask whether the new purchase is still worth the total commitment.
How It Helps You Shop Smart
Affirm isn’t just about helping you buy now and pay later. It’s designed to make you a smarter shopper. By breaking down the cost, it encourages you to think about your budget and make informed financial decisions. Plus, it’s a great way to build credit, as long as you stick to your payment plan.
Screenshots
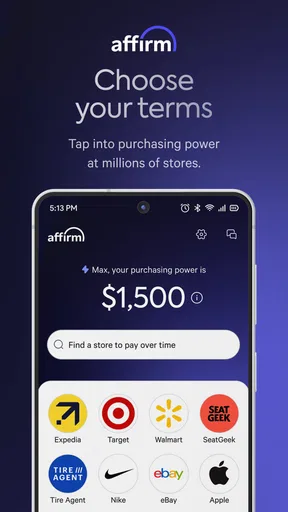
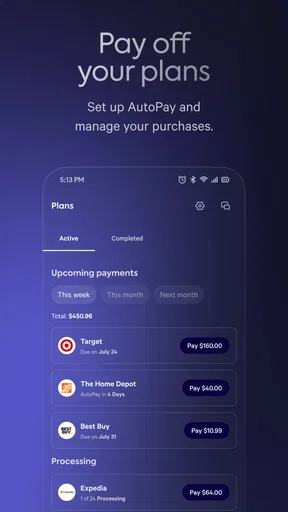
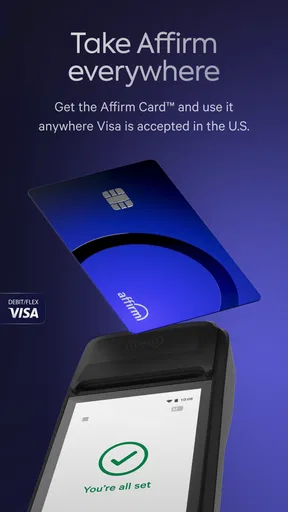
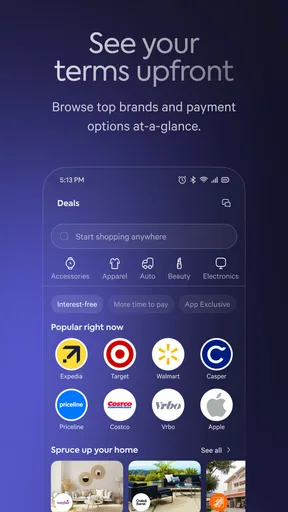
One thing to keep in mind, though, is the interest rate. It varies based on your credit and the retailer, so always check the details before you proceed. It’s like having a friendly nudge to remind you to shop wisely.
Choosing between Affirm and familiar payment options
Compared with paying upfront from a bank account, a payment plan can preserve cash in the short term, but it creates future obligations and may cost more depending on the offer. A credit card can be more familiar and may suit someone who already tracks its statement and pays it as planned; Affirm is worth considering when its specific checkout terms are clearer or more suitable for that purchase. A standard retailer payment plan may be another option, so I would compare the total cost and due dates rather than assuming one method wins every time.
Affirm is not the right fit if you need to avoid borrowing, if you are unsure about your income over the repayment period, or if you tend to lose track of multiple due dates. In those cases, paying upfront, delaying the purchase, or choosing a less expensive alternative is safer. The convenience is real, but convenience should not substitute for affordability.
Questions I would settle before relying on it
Will every shop accept it? No: the app is useful when the retailer offers Affirm at checkout, so I would confirm that option is available for the item I want instead of planning around it. Will every user see the same plan? The offer should be assessed on its own displayed terms; I would never assume a friend’s schedule or rate will apply to me.
Can the app help me remember what I owe? Its account and payment schedule views, along with alerts and reminders, can help me keep plans visible, but I would still check the schedule myself and make sure my payment method and available funds are in order. Does splitting a purchase automatically help my credit? I would not count on that as the reason to use it. Credit outcomes depend on how an account is handled and reported, so my decision would rest on whether the purchase and repayments make sense for my finances.
Remaining trade-offs and sensible habits
Affirm can make the checkout decision feel smooth, which is precisely why I would build in a short pause. Read the full cost, confirm the dates, and consider how the plan interacts with other obligations. A notification is helpful, but it cannot decide whether a purchase is wise or make an unaffordable plan manageable.
I would also keep the app’s role narrow: use it to review an eligible purchase and monitor the payments you have chosen, not as a shopping list or a substitute for a household budget. A simple note of due dates alongside regular bills can make overlapping commitments easier to spot. If the figures feel tight or unclear, stop and compare the upfront option and other available ways to pay before proceeding.
Final Thoughts
In a world where instant gratification often comes at a cost, Affirm offers a breath of fresh air. It’s a reliable tool for those of us who want to enjoy the things we love without the financial strain. Whether you’re buying a new phone, a cozy couch, or planning a little retail therapy, this app helps you do it responsibly.
So, if you’re looking for a way to manage your shopping expenses with ease and transparency, give Affirm a try. It might just become your new favorite shopping companion.
Who I’d recommend it to, and what I’d watch
I’d recommend trying it to someone who has a specific purchase in mind, wants to compare payment schedules before deciding, and is comfortable checking due dates against a real monthly budget. I would be less likely to recommend it to someone who is already juggling repayments or who tends to treat available credit as extra income. In that situation, the app’s convenience could make it easier to take on more than intended.
Going forward, I would judge the app by the clarity of the terms shown for each purchase and by how easily I can keep track of existing commitments. Version 3.402.1 is the current reference point, but future changes should be assessed by what they actually do in the app rather than by a version number alone. For now, my advice is simple: use the payment breakdown as a decision aid, compare it with paying upfront, and proceed only when the full schedule fits comfortably.
Affirm: Buy now, pay over time FAQ
What is Affirm and how does it work?
Affirm is a payment solution that allows users to make purchases and pay for them over time with no hidden fees. Once you choose Affirm at checkout, you'll need to provide some basic information to get a real-time decision. If approved, you can select a payment plan that suits your budget, ranging from three months to a year.
Are there any interest charges or fees with Affirm?
Affirm offers transparent financing with no hidden fees. The interest rates can vary based on your creditworthiness, with some purchases offering 0% APR. You'll see exactly what you'll owe upfront, and you won’t encounter any late fees or compounding interest, making it easy to manage your budget.
Is using Affirm safe and secure?
Yes, Affirm is committed to safeguarding your information with industry-standard security protocols. Your data is encrypted, and they employ robust measures to protect against unauthorized access. Additionally, Affirm does not sell your data to third parties, ensuring your privacy is respected.
How does Affirm impact my credit score?
Affirm performs a soft credit check when you apply, which does not affect your credit score. However, if you choose to proceed with a payment plan, your payment history and credit usage may be reported to credit bureaus. Timely payments can positively impact your credit score, while missed payments could have negative effects.
Can I use Affirm for any type of purchase?
Affirm is available at a wide range of online and physical retailers, from electronics to fashion. However, not all merchants offer Affirm as a payment option. It's best to check if Affirm is available at checkout with the retailer you wish to purchase from. Some exclusions may apply based on the merchant's policies.